Global Economy Strains Under Geopolitical Energy Friction and Shifting Tech Valuations
Surging capital investment in artificial intelligence and resilient labor markets are colliding with persistent inflation and volatile energy routes, leaving central banks wary of premature policy easing.
A Complex Convergence of Momentum and Strain
The global economic landscape has arrived at a pivotal juncture where domestic economic activity continues to exhibit surprising endurance, yet remains shadowed by systemic vulnerabilities. Recent developments across international markets reveal a distinct push-pull dynamic: on one side, sustained capital expenditures linked to next-generation computing infrastructure and buoyant labor conditions provide a robust growth foundation. On the other, recurring volatility across vital global trade corridors and stubborn inflationary pressures prevent central banks from declaring victory in their multi-year battle against price spikes.
International financial institutions and central bankers emphasize that underlying demand in advanced economies has performed better than many analysts predicted just months ago. Continued consumer spending and industrial capital deployments have insulated major trading partners from what might have otherwise developed into broad stagflation. However, this momentum has not materialized evenly across borders. Emerging economies find themselves grappling with widening trade deficits and higher imported energy costs, while policymakers in mature economies must decide whether existing monetary restrictions are sufficient to contain persistent headline price pressures.
The AI Capital Surge and Growing Market Scrutiny
At the center of domestic corporate expenditure is an unprecedented wave of technological investment. Analysts estimate that annual capital spending on artificial intelligence data infrastructure, hardware, and integration will represent an outsized share of global gross domestic product through the turn of the decade, surpassing the rollout trajectories of past industrial tech booms. This capital deployment has acted as a primary growth stabilizer, driving demand for semiconductors, specialized real estate, and electrical grid upgrades.
Yet financial markets have begun demonstrating acute sensitivity to the concentration of corporate performance within a handful of mega-cap technology firms. Significant share declines across hyperscalers and key semiconductor manufacturers recently erased substantial market capitalization in brief trading sessions, sparking comparisons to late-1990s tech cycle corrections. Regulatory scrutiny surrounding technology dominance and data sovereignty has compounded these jitters. Multilateral regulators have warned that the intersection of lofty valuations, corporate leverage, and concentrated cross-investments between foundational model developers and cloud infrastructure giants creates a transmission channel through which localized earnings disappointments could trigger broader economic reverberations.
Commodity Pressures and Trade Route Disruptions
Even as innovation spending anchors the corporate sector, traditional industrial inputs remain hostage to geopolitical flashpoints. Tensions across the Gulf region and maritime shipping corridors, such as the Strait of Hormuz and the Red Sea, have injected a persistent risk premium into global crude, refined product, and fertilizer supply chains. While sporadic diplomatic overtures and inventory rebalancing have occasionally capped weekly barrel prices, economists note that global energy distribution networks remain historically fragile.
Standard Chartered research indicates that even under an optimistic timeline for conflict resolution, normalizing petroleum and petrochemical maritime logistics requires weeks to months, sustaining elevated operational costs worldwide. Developing economies remain particularly exposed to this dynamic. Nations with heavy import dependency have seen foreign exchange reserves drop significantly as fuel bills mount, forcing governments to negotiate tighter import financing agreements and domestic subsidy reductions. A structural shift is underway where access to and control of foundational commodities serves both as economic leverage and as an active geopolitical instrument.
Central Banks Navigate High Inflation and Sticky Labor Trends
Faced with this divergent reality, monetary authorities have reinforced a cautious, data-dependent stance. In the United States, Federal Reserve officials recently upgraded their characterization of economic expansion to a strong pace, supported by historically low unemployment, strong productivity figures, and better-than-expected payroll additions. However, persistent core inflation and volatile commodity markets have led policymakers to keep benchmark policy rates elevated, pushing back against aggressive market expectations for sustained monetary easing.
Across the Atlantic, European monetary leadership faces comparable dilemmas. The Bank of England has signaled that additional borrowing cost hikes cannot be ruled out if wage growth and import costs fail to soften, even as local equity markets and manufacturing sectors experience subdued output. In the euro area, divergence between corporate resilience and domestic consumer frustration is palpable. While certain southern European economies have benefited from selective trade tariff adjustments and services activity, living costs continue to strain household budgets, spurring civil unrest and policy interventions regarding property taxation and social safety nets.
Emerging Markets and Currency Balancing Acts
In Asia, policymakers are executing intricate currency and credit maneuvers to safeguard domestic recovery. The People’s Bank of China recently raised its foreign-currency deposit reserve requirement ratio to moderate the rapid appreciation of the onshore yuan and steady cross-border capital flows. Concurrently, Beijing continues to lean into aggressive international trade outreach, expanding shipments of electric passenger vehicles, commercial machinery, and green technology to capture foreign market share—a development that has stoked renewed trade defense measures and protective tariffs across North American and European industrial hubs.
For developing markets throughout South Asia and the Global South, the principal defense mechanism against imported inflation has been the absence of an unchecked, aggressive surge in the value of the U.S. dollar, which has spared central banks from an acute debt-service and currency crisis. Nonetheless, fiscal authorities face mounting debt service obligations, leaving little maneuvering room should energy shocks deepen or export growth in key European trading partners deteriorate further.
Outlook: Walking the Tightrope
As the final quarter of the year unfolds, the trajectory of the global economy hinges on whether high-tech capital expenditures can continue to compensate for structural energy frictions. If productivity gains from generative digital infrastructure materialize swiftly, corporate margins may weather elevated financing and logistics expenses. Conversely, if geopolitical entanglements continue to disrupt key shipping lanes or if technology equity adjustments prompt a broader pullback in corporate risk appetite, central banks will confront the unenviable task of defending price stability in an increasingly fragmented, cost-burdened international trade regime.
Recommended for you
Similar to “Economy”
Global Economy Navigates AI Boom, Persistent Inflation, and Energy Shocks
Surging capital investment in artificial intelligence and resilient labor markets are propelling global activity, even as volatile energy markets and sticky services inflation constrain central bank policy.
A Fragile Balancing Act: Global Economy Strains Under Resurgent Inflation, Geopolitical Friction, and an Unbalanced AI Boom
While aggressive corporate spending on artificial intelligence and resilient labor markets continue to prop up headline growth, central bankers confront persistent wage and service price pressures alongside mounting geopolitical and debt risks.
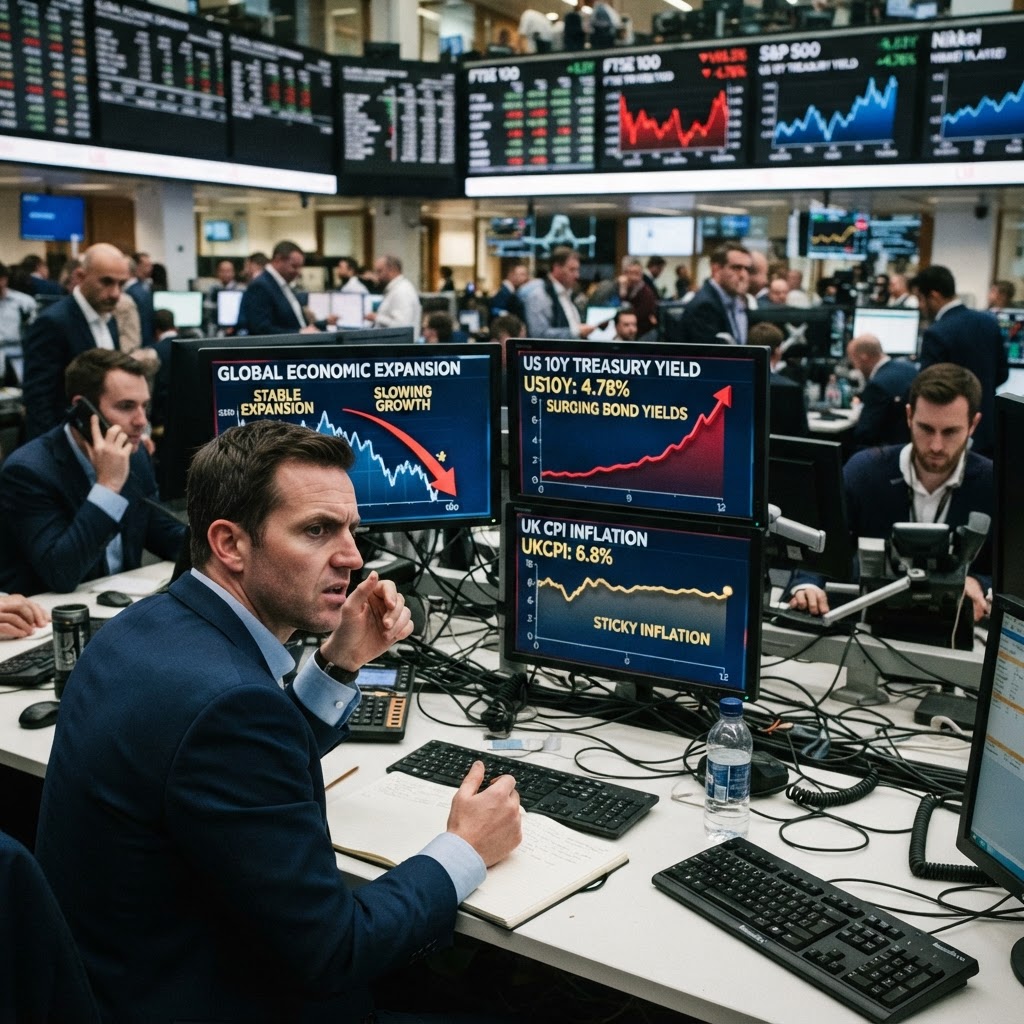
Sticky Inflation and Surging Bond Yields Confront the Global Economic Expansion
Central banks face renewed policy dilemmas as resilient job numbers, persistent commodity shocks, and massive artificial intelligence capital expenditures combine to push bond yields upward and complicate the inflation outlook.