Sticky Inflation and Surging Bond Yields Confront the Global Economic Expansion
Central banks face renewed policy dilemmas as resilient job numbers, persistent commodity shocks, and massive artificial intelligence capital expenditures combine to push bond yields upward and complicate the inflation outlook.
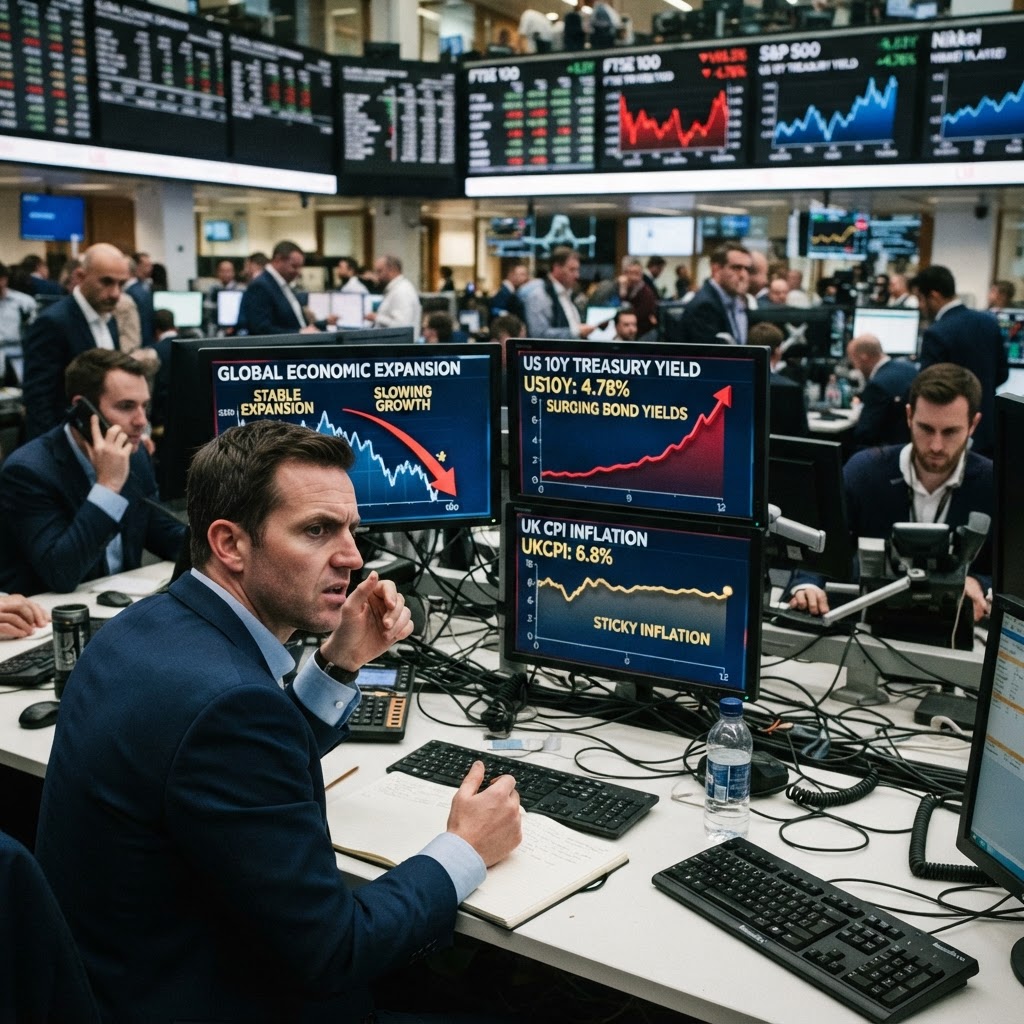
A Complex Convergence of Growth and Cost Pressures
The global macroeconomic environment is navigating an increasingly volatile transition. While underlying economic activity has demonstrated notable resilience—buoyed by tight labour markets and heavy capital deployment into transformative technologies—policymakers find themselves constrained by persistent inflationary undercurrents. As detailed in the Reserve Bank of Australia's Statement on Monetary Policy, recent months have witnessed an accumulation of global cost pressures driven by protracted Middle Eastern supply frictions and strong industrial demand, complicating efforts to guide inflation durably back to target levels.
International forecasters anticipate that global output will expand at a measured pace around 3.0% in 2026 before edging toward roughly 3.2% to 3.3% next year, according to analyses from the Conference Board and CaixaBank Research. Nevertheless, divergence remains sharp across major regions. The United States continues to demonstrate surprising domestic vigor, even as European economies encounter sluggish industrial production and China faces a gradual structural deceleration toward 4.0% growth. This uneven baseline leaves global markets vulnerable to sudden financial repricing.
Labor Resilience and the Stubborn Inflation Tape
In the United States, recent macroeconomic readings have highlighted the persistent tension between sturdy hiring and sticky pricing dynamics. The latest establishment payroll data surprised market observers by registering 165,000 new positions for October, maintaining unemployment at a historically low 4.1%, as highlighted in the Deloitte Weekly Global Economic Update. Yet, consumer and wholesale cost indicators continue to suggest that the disinflationary process has reached an uncomfortable plateau.
Government data published in mid-November revealed that the U.S. producer price index (PPI) advanced 0.3% month-on-month and remained elevated at 6.5% on an annualized basis, as reported by RTTNews. While wholesale figures eased marginally compared to prior spikes, core metrics remain firm. Together with personal consumption expenditures (PCE) readings settling well above the Federal Reserve's 2.0% objective, these figures have curtailed market hopes for widespread monetary easing, reinforcing expectations that borrowing costs will stay restrictive for an extended period.
Central Banks Tighten the Screws
The resurgence of price pressures has spurred central banks in advanced economies to reconsider their monetary postures. As chronicled in the Banco de la República Financial Markets Report, the Federal Reserve enacted a reference interest rate increase for the first time since 2023, and institutions such as the Bank of England have similarly adjusted their stances to counteract secondary inflation risks. Emerging market monetary authorities have responded with equal vigilance; in Latin America, Colombia raised its policy benchmark to 12.25%, while Brazil held its Selic rate firmly at 13.75%.
This renewed hawkishness has reverberated heavily across international debt markets. According to The Rio Times, benchmark U.S. 10-year Treasury yields breached the 5.14% threshold in recent sessions, lifting sovereign risk premiums across both developed and developing economies. As yields climb, capital flows have become more volatile, prompting corrections in sovereign paper, particularly across long-duration curves where investors demand greater compensation for fiscal and inflation uncertainties.
Technology Investments and Geopolitical Headwinds
Financial asset markets have reacted with heightened sensitivity to the intersection of borrowing costs and technological investment. Growth and technology equities, which had rallied extensively on enthusiasm surrounding artificial intelligence infrastructure and data center construction, have absorbed significant selling pressure as elevated discount rates weigh on long-dated valuations. Market analysis from Crossmark Global Investments notes that elevated bond yields, alongside questions regarding the timing and profitability of massive AI capital outlays, have fueled bouts of volatility across major equity indices.
Simultaneously, broader supply-side disruptions continue to inject friction into production pipelines. Disruptions to maritime transport and regional energy logistics have kept oil, refined petroleum, and vital industrial inputs substantially above prior baselines. Moreover, agricultural markets face compounding stress from extreme weather anomalies, including climate shocks examined by the United Nations, which have driven up farming, fertilizer, and transportation expenditures across developing regions.
The Narrowing Policy Runway
Looking ahead, the global economic landscape faces a narrowing corridor of policy options. With public debt burdens elevated in advanced nations and sovereign borrowing premiums widening across emerging markets, governments possess diminished fiscal space to stimulate growth should demand soften. Consequently, economic trajectory over the coming quarters will depend on whether labor resilience and productivity-enhancing investments can outpace the drag of high interest rates, or whether persistent commodity shocks will ultimately entrench a prolonged period of higher-for-longer capital costs.
Recommended for you
Similar to “Global Economy”
Global Economy Navigates AI Boom, Persistent Inflation, and Energy Shocks
Surging capital investment in artificial intelligence and resilient labor markets are propelling global activity, even as volatile energy markets and sticky services inflation constrain central bank policy.
Sticky Inflation and Surging Bond Yields Confront the Global Economic Outlook
Renewed spikes in energy costs, stubborn consumer inflation, and surging sovereign bond yields are challenging central banks and policymakers across major economies.
The Dual-Speed Dilemma: Global Economy Trapped Between Tech Euphoria and Inflationary Friction
Central bankers face an unprecedented policy puzzle as massive artificial intelligence capital spending drives resilience in advanced economies while persistent energy shocks, swelling public debt, and sticky price pressures keep interest rates elevated.