Sticky Inflation and Surging Bond Yields Confront the Global Economic Outlook
Renewed spikes in energy costs, stubborn consumer inflation, and surging sovereign bond yields are challenging central banks and policymakers across major economies.
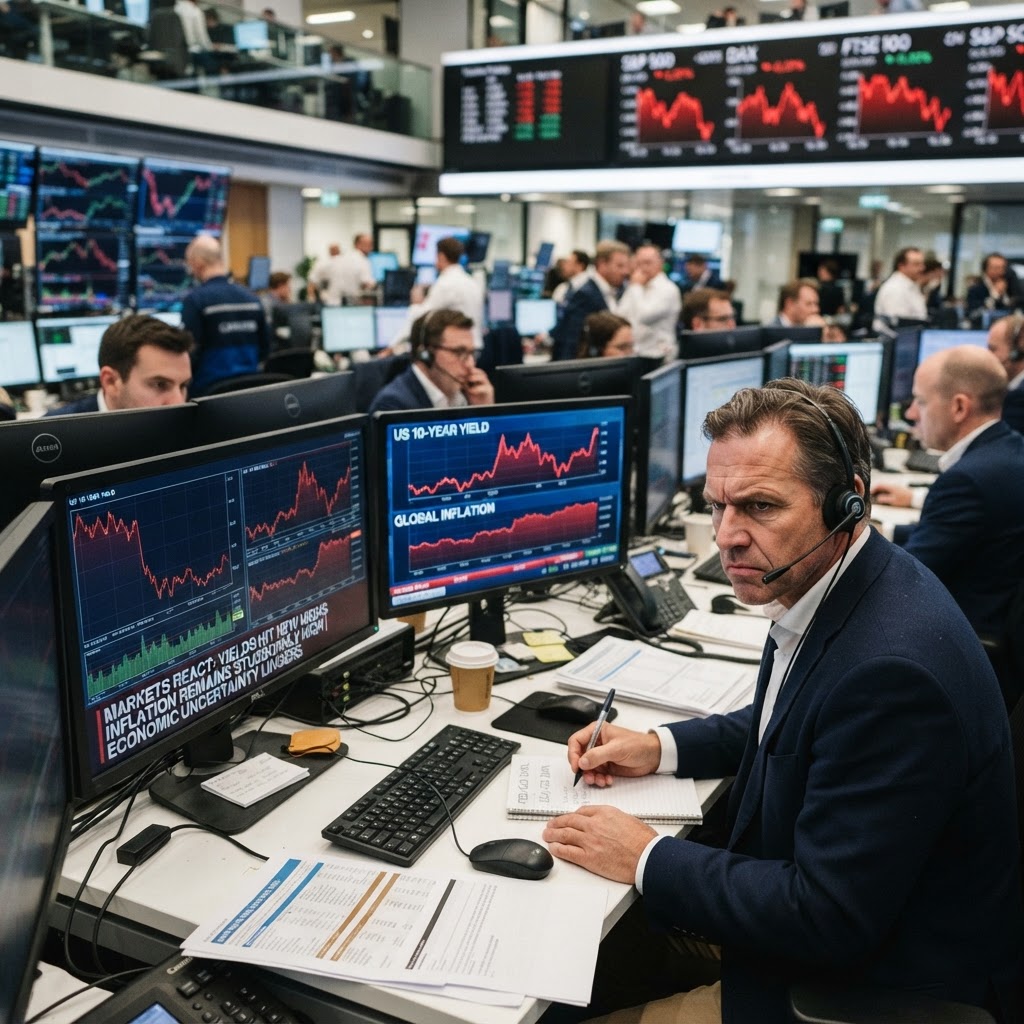
Turbulent Tailwinds and Persistent Inflation Pressures
The global economy faces a complex tug-of-war between resilient consumer activity and reignited inflationary pressures. Recent economic updates indicate that headline inflation across key developed markets remains obstinately high, heavily driven by rebounding energy commodities and shifting geopolitical risks. Consumer price gauges have plateaued well above central bank targets, complicating the path for monetary easing and stoking market anxiety over potential policy tightening.
In the United States, recent price indices reflected an annual consumer price increase holding firm at elevated levels, driven in large part by double-digit annual increases in energy components. Although core goods prices have shown signs of stabilizing in select categories, volatile utility and fuel costs continue to pass through into broader logistics, services, and everyday consumer expenditures. In Europe, escalating energy concerns and historically low liquefied natural gas inventories ahead of the cooler months have added to the region's inflation risks, testing whether recent structural diversification of energy suppliers is sufficient to prevent new price shocks.
Sovereign Debt Markets Face Mounting Yield Pressures
Financial markets have responded decisively to these macroeconomic conditions. Global bond markets have experienced a pronounced sell-off, pushing long-term benchmark yields close to multi-year highs. The yield on the benchmark 10-year U.S. Treasury has hovered near 5 percent, reflecting rising term premiums as investors factor in higher-for-longer policy rates, heavy government debt issuance, and ongoing fiscal deficits.
Policymakers and market analysts remain divided on how to interpret these surging yields. On one hand, government fiscal authorities have argued that market movements are amplified by risk aversion rather than underlying fundamentals, intervening with tactical bond repurchases to moderate yield volatility. Conversely, institutional economists emphasize that higher borrowing costs serve a disciplining role in capital allocation, reversing the distortions caused by ultra-low interest rates. In addition, massive capital expenditures in artificial intelligence, digital infrastructure, and technological upgrades are generating expectations of long-run productivity enhancements, which historically support higher real interest rates.
Consumer Spending and Labor Market Bifurcation
Despite rising interest rates and persistent price increases, domestic demand across several advanced economies has displayed notable durability. In the United States, data from the Bureau of Economic Analysis revealed continued monthly expansion in disposable personal income and a solid uptick in personal consumption expenditures. Households have sustained personal spending across essential and discretionary items, even as personal saving rates moderate to around 4 percent.
Underneath the resilient spending figures, however, labor markets and sector performance exhibit striking divergence. Employment gains in major economies have become heavily concentrated in services—particularly healthcare, social assistance, and hospitality—while industrial output, manufacturing, and tech-adjacent roles show muted headcount growth. Analysts observe that structural shifts in labor demand, combined with demographic aging across Western economies, are beginning to alter labor supply dynamics and public balance sheets.
Global Trade Imbalances and the Road Ahead
International commerce presents an equally mixed landscape. Widening trade deficits in major import-driven economies, such as the U.S. current account deficit expanding amid sustained goods imports, highlight the persistent appetite of consumers for cross-border commodities. Concurrently, export engines in emerging markets and East Asia continue to leverage industrial manufacturing, despite ongoing tariff frictions and shifts in global supply chain architecture.
Looking toward the coming quarters, central banks find themselves navigating an increasingly narrow corridor. With central banks balancing sluggish trade, elevated government borrowing costs, and stubborn consumer price pressures, any sudden resurgence in commodity bottlenecks could trigger fresh monetary policy friction. As economic leaders assemble for autumn policy meetings, the durability of household demand and the trajectory of energy markets will determine whether the global economy can achieve a sustainable glide path or enter another phase of stagflationary turbulence.
Recommended for you
Similar to “Economy”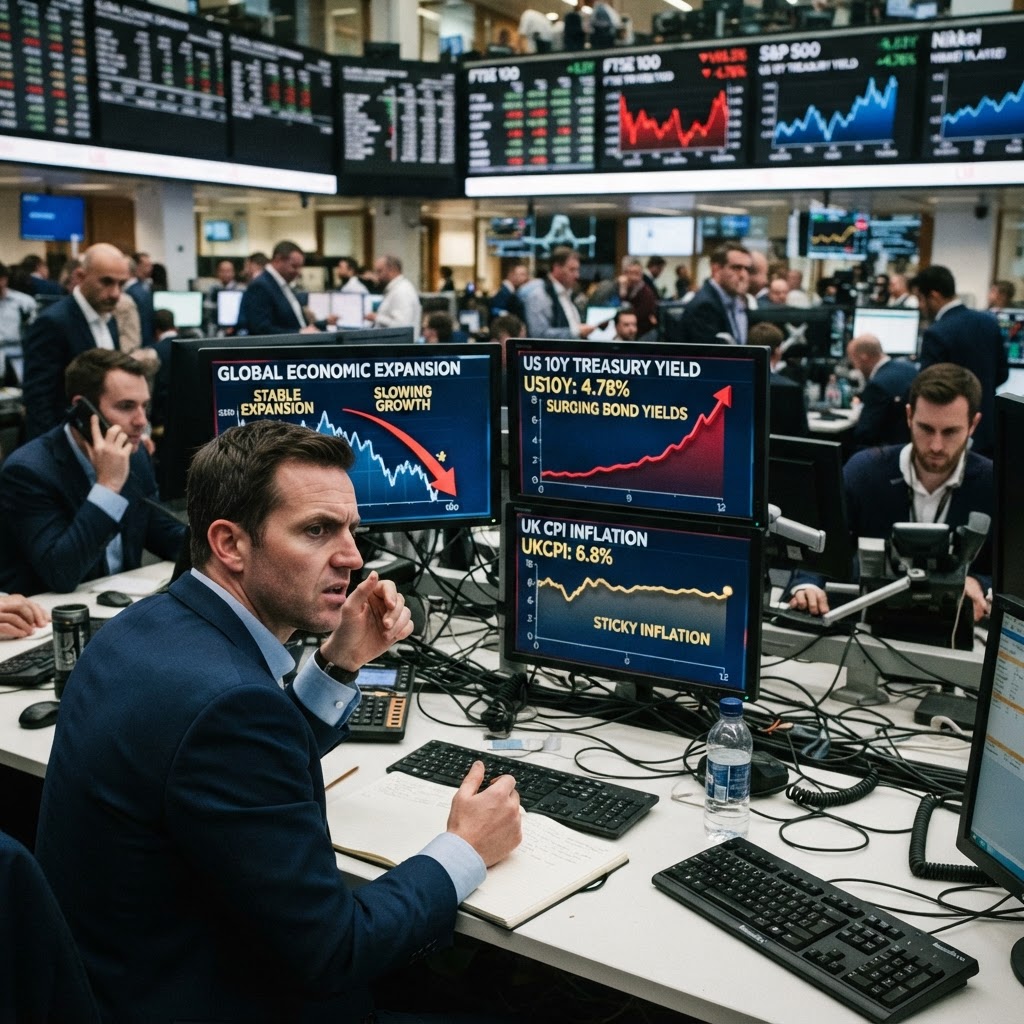
Sticky Inflation and Surging Bond Yields Confront the Global Economic Expansion
Central banks face renewed policy dilemmas as resilient job numbers, persistent commodity shocks, and massive artificial intelligence capital expenditures combine to push bond yields upward and complicate the inflation outlook.
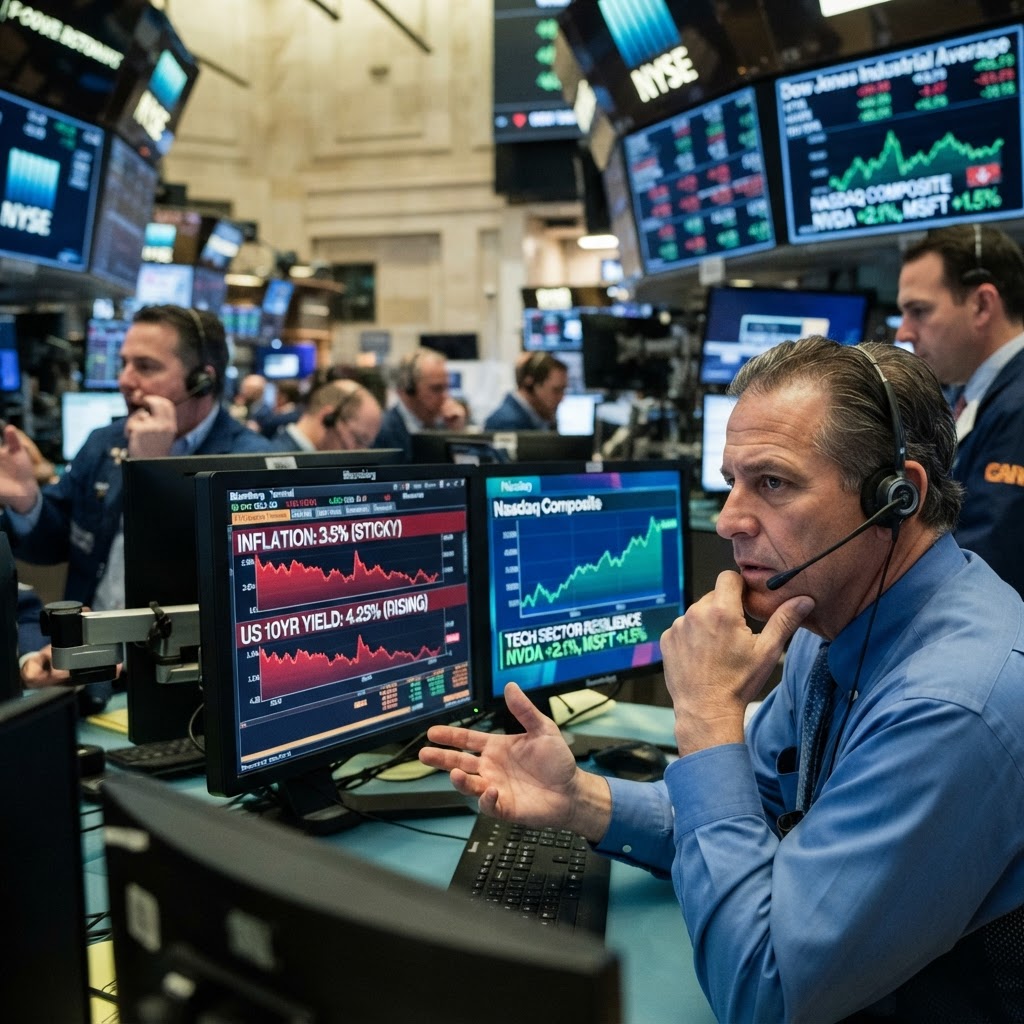
Sticky Inflation and Rising Yields Collide with Tech-Driven Market Resilience
Stubborn consumer price figures and hawkish central bank warnings are colliding with easing geopolitical tensions and an artificial intelligence investment boom, leaving the global economic outlook balanced on a knife-edge.
Crosscurrents in the Global Economy: Energy Shocks, Central Bank Divergence, and the AI Capex Gamble
As persistent geopolitical strife and energy market turbulence challenge macroeconomic stability, central banks confront stubborn inflation while surging technology investments test broader economic resilience.