Sticky Inflation and Rising Yields Collide with Tech-Driven Market Resilience
Stubborn consumer price figures and hawkish central bank warnings are colliding with easing geopolitical tensions and an artificial intelligence investment boom, leaving the global economic outlook balanced on a knife-edge.
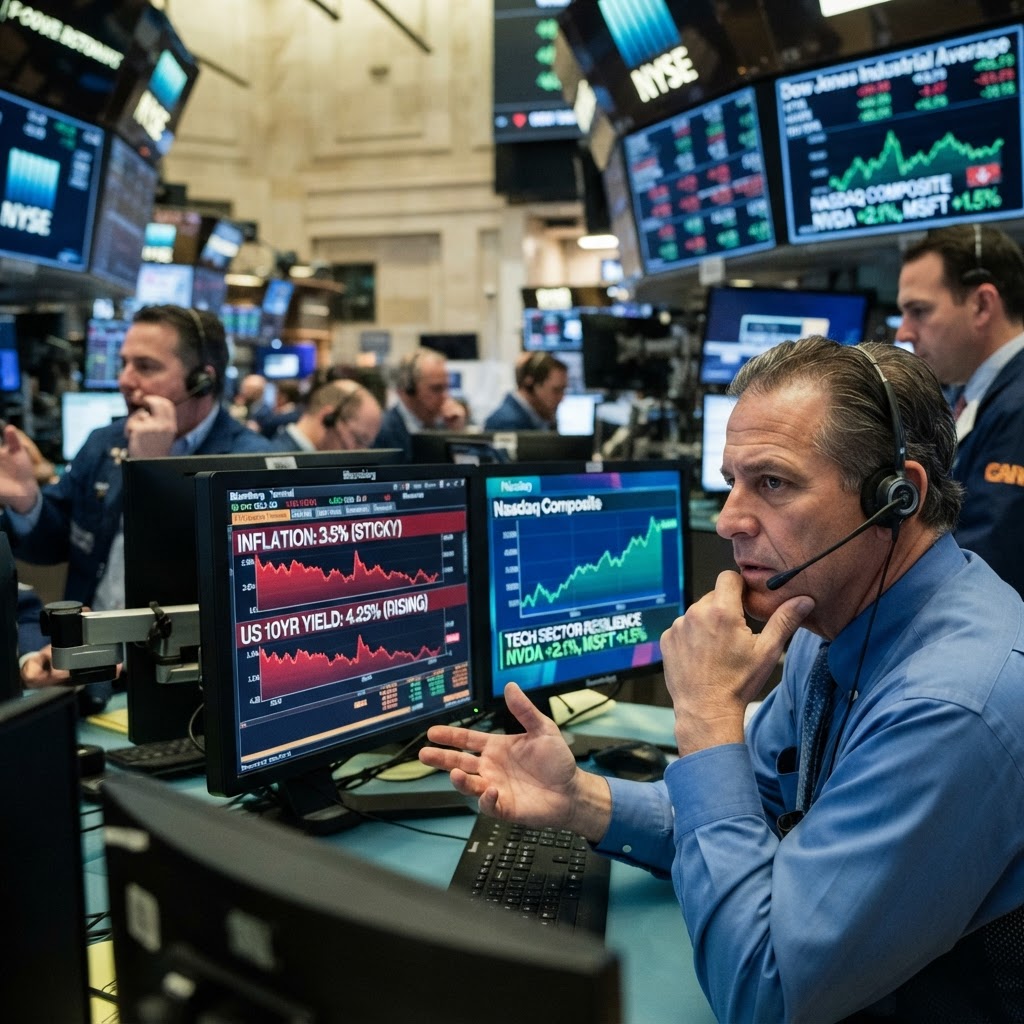
A Complex Convergence of Relief and Restraint
Global financial markets and macroeconomic planners are navigating an extraordinarily turbulent crosscurrent. On one hand, equity benchmarks have seen sharp relief rallies fueled by diplomatic efforts to de-escalate tensions in the Middle East, coupled with a welcome retreat in crude benchmarks from recent peaks. On the other hand, stubbornly persistent consumer price inflation and mounting employment costs in major advanced economies are puncturing expectations of an imminent monetary easing cycle, forcing central banks to keep benchmark interest rates higher for longer.
International observers and policy institutions note that while broader economic activity has demonstrated remarkable durability, the underlying foundations of that resilience are increasingly fragile. A sustained infrastructure and capital expenditure boom driven by artificial intelligence continues to prop up corporate earnings, yet government bond yields hover near multi-year highs as traders grapple with the reality that inflation is proving far harder to extinguish than previously anticipated.
The Inflation Trap and the Return of Hawkish Central Banking
In the United States, fresh Consumer Price Index data delivered a sobering blow to hopes that price pressures would smoothly glide toward central bank targets. The release revealed higher-than-expected headline and core readings, triggering an immediate selloff in sovereign debt markets and driving the benchmark 10-year Treasury yield firmly toward the 5% threshold. Hawkish commentary from Federal Reserve officials quickly followed, with policymakers warning that additional rate hikes remain on the table if demand and underlying service inflation refuse to cool.
Compounding the problem for monetary authorities is the structural divergence emerging within labor markets. While nominal wage growth across private sector employment has shown signs of plateauing, corporate benefit overheads—led by surging employer healthcare and hospitalization costs—continue to advance at a rapid clip. In Europe and Latin America, price dynamics mirror this stubborn trend; Eurozone core metrics have accelerated, and emerging market powerhouses like Brazil are witnessing their central banks grapple with sticky domestic inflation forecasts, curbing their room to provide economic stimulus.
Uneven Expansion and Widening Global Disparities
Behind the headline resilience of the world economy lies a dramatic geographic and sectoral concentration of growth. Multilateral institutions including the International Monetary Fund have highlighted that the overwhelming majority of global expansion is now generated by a shrinking cohort of dominant economies. While advanced Asian manufacturing hubs and North American technology centers benefit from relentless capital allocation toward next-generation computing hardware, domestic consumption in major European economies remains sluggish, held back by high borrowing costs and lingering supply-side frictions.
Trade imbalances are also expanding in unexpected ways. Despite headwinds in international freight and regional trade frictions, China has posted trade surpluses exceeding historic records, driven in large part by strong shipments of industrial components, renewable energy technology, and electronics. Yet domestic consumer sentiment across several key emerging and developed markets remains tempered by elevated living expenses and tight credit availability, exposing vulnerable supply chains to sudden demand shocks.
The AI Capital Surge and Growing Sovereign Debt Headwinds
Perhaps the most potent counterweight preventing an outright global economic contraction has been the wave of capital expenditure linked to artificial intelligence and advanced digital infrastructure. Enormous venture financing, public debuts, and multi-billion-dollar enterprise expansions have generated an aggressive buffer against conventional cyclical headwinds. Major technological players have managed to keep corporate earnings buoyant, limiting downside momentum in major equity indices and fueling sporadic market surges.
However, credit rating agencies and international watchdogs increasingly caution that this technology-led boom carries systemic vulnerabilities. Credit default swap spreads for debt tied to massive data center investments have begun to show pockets of underperformance, reflecting investor apprehension over the long payback horizons and massive energy requirements of these facilities. Simultaneously, sovereign balance sheets offer far less margin for error than in previous cycles; aggregate global public debt is expanding toward unprecedented peacetime levels relative to gross domestic product, leaving governments with virtually no fiscal ammunition should another external supply shock hit.
The Road Ahead: Navigating Monetary Uncertainty
As policymakers, corporate treasurers, and investors look toward the coming quarters, the margin for error has narrowed considerably. The recent pullback in energy prices offers modest breathing room for energy-importing economies, but it remains heavily dependent on sustained diplomatic stability in critical transit corridors and oil-producing regions.
Ultimately, the global economy appears caught in an uneasy transitional phase. While technological disruption and strong corporate balance sheets continue to supply genuine momentum, the unforgiving reality of elevated cost of capital, mounting debt servicing burdens, and unyielding inflation metrics means that the era of cheap liquidity is definitively over. Navigating the remainder of the business cycle will require both fiscal discipline and pinpoint execution from monetary authorities as they strive to engineer an orderly descent without provoking a broader financial stall.
Recommended for you
Similar to “Global Economy”
Global Economy Strains Under Geopolitical Energy Friction and Shifting Tech Valuations
Surging capital investment in artificial intelligence and resilient labor markets are colliding with persistent inflation and volatile energy routes, leaving central banks wary of premature policy easing.
Fragile Resilience: Global Economy Navigates Energy Pressures, Rising Yields, and Tech Headwinds
While third-quarter output reflects ongoing momentum in key markets, rising sovereign bond yields, stubborn energy-driven inflation, and concentrated bets on artificial intelligence pose mounting risks to worldwide financial stability.
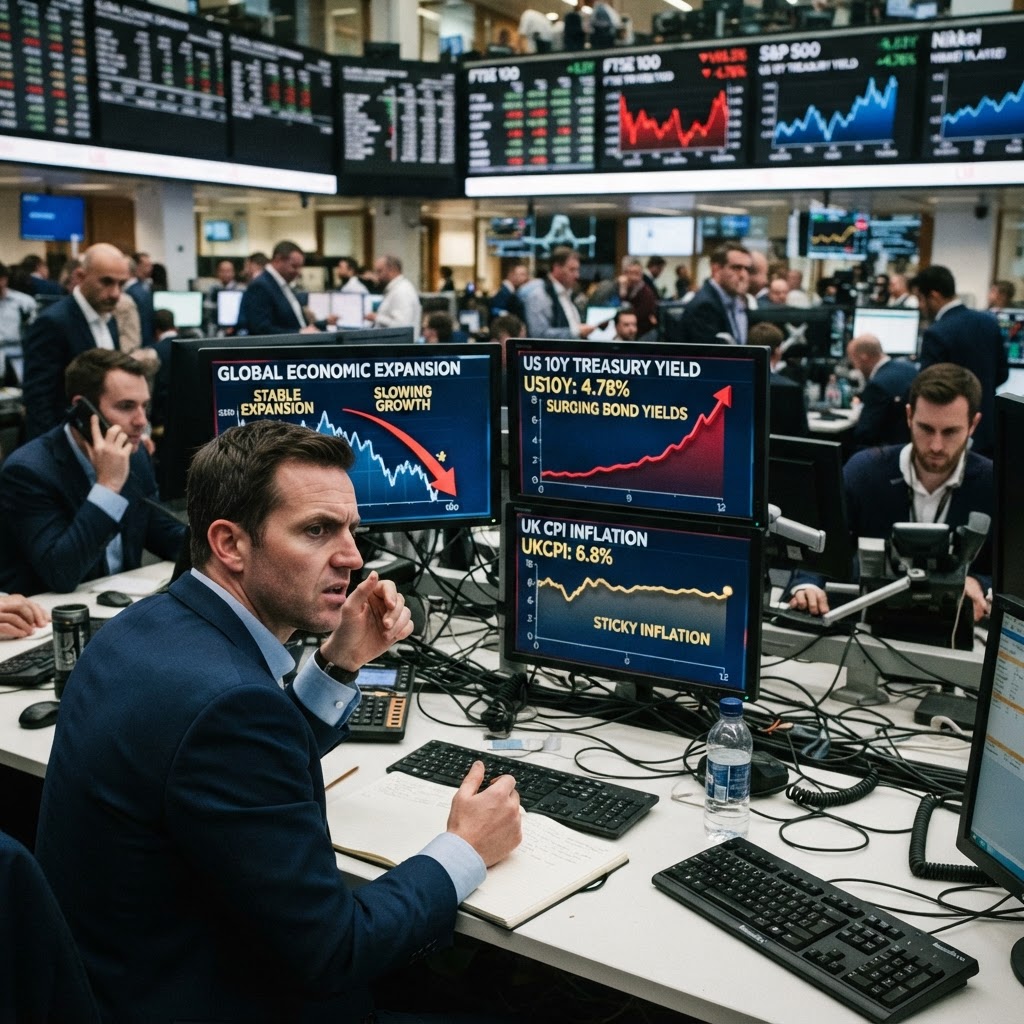
Sticky Inflation and Surging Bond Yields Confront the Global Economic Expansion
Central banks face renewed policy dilemmas as resilient job numbers, persistent commodity shocks, and massive artificial intelligence capital expenditures combine to push bond yields upward and complicate the inflation outlook.