Global Economy Navigates High-Tech Surge Amid Stubborn Energy Shocks and Borrowing Strains
While sustained capital expenditure in computing infrastructure and artificial intelligence buoys global trade and financial benchmarks, resurgence in commodity costs and mounting sovereign debt yields present fresh hurdles for monetary policymakers.
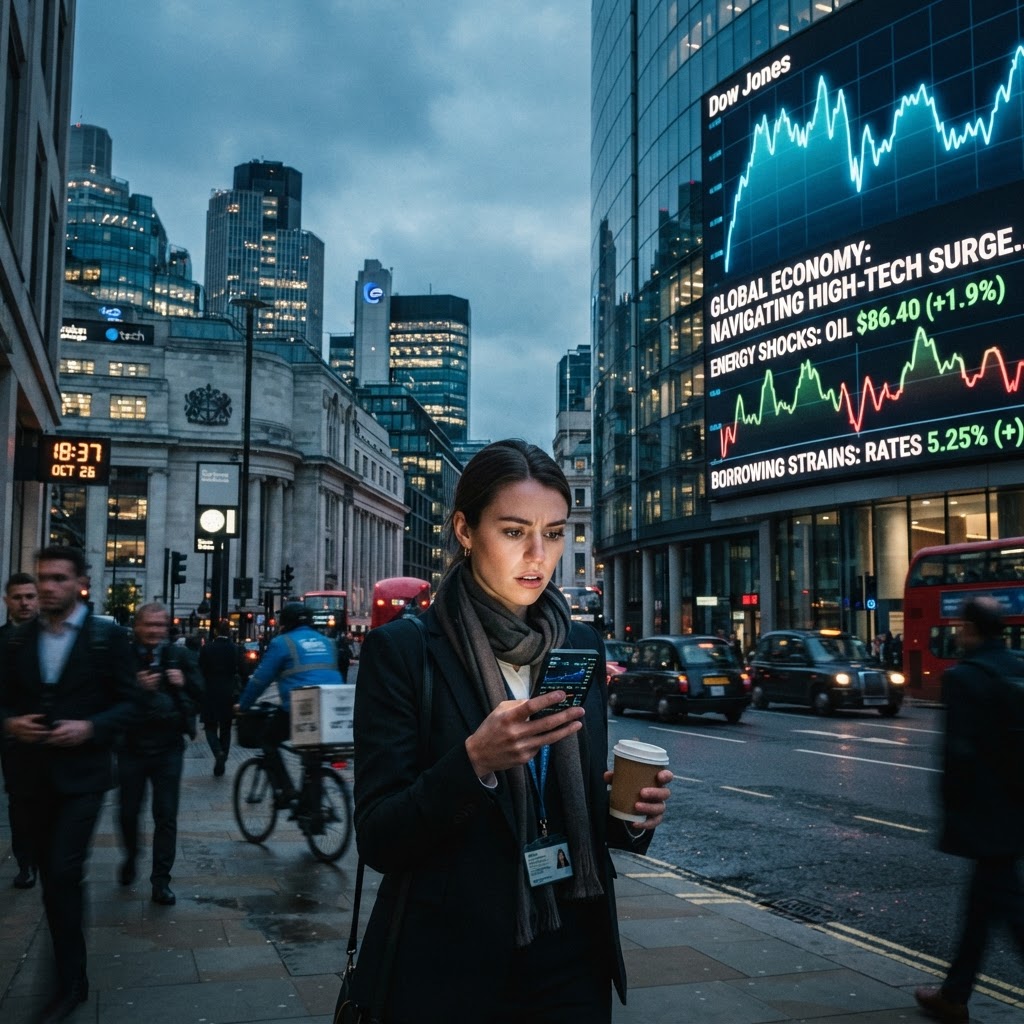
The Two-Speed Dynamic of Global Expansion
The international economic landscape is displaying a stark divergence as robust technological investment collides with renewed cost-of-living pressures and fiscal tightening. Over the past several days, fresh macroeconomic assessments across major regions highlight an economy demonstrating resilience in headline activity, yet vulnerable to localized bottlenecks and policy constraints. Expansion across the Asia-Pacific Economic Cooperation (APEC) zone, for instance, has held above earlier estimates, supported primarily by strong hardware demand, computing infrastructure deployment, and semiconductor shipments. However, international observers warn that this technological tailwind is disguising underlying friction caused by volatile energy markets and higher borrowing costs.
In the United States, consumer activity and private capital expenditures have sustained quarterly momentum, although recent high-frequency indicators indicate a cooling labor market and mixed manufacturing sentiment. Meanwhile, the Eurozone is grappling with widening internal imbalances. While peripheral economies such as Spain have continued to expand steadily, traditional industrial engines including Germany and France have experienced stagnation or minor contractions, undermined by elevated operational overheads and fragile consumer confidence.
Commodity Pressures and Monetary Headwinds
The primary complication for global financial stability remains the stubborn trajectory of inflation. Over recent months, international commodity indices have registered sharp upward adjustments. Crude oil benchmarks, liquefied natural gas contracts, and thermal coal have surged in response to shipping reroutings and persistent geopolitical friction across strategic transport corridors. Agricultural commodities, including vegetable oils and grains, have similarly faced upward price pressure exacerbated by adverse meteorological shifts.
These supply-side shocks are complicating the roadmap for central banking authorities. Rather than an orderly return to lower benchmark policy rates, fixed-income markets have experienced renewed yield spikes, with the United States 10-year Treasury yield once again holding above five percent. In several emerging and developed markets, central bankers have signaled continued vigilance or implemented tactical rate increases to preempt secondary inflationary impulses from taking root across general consumer baskets.
Tech Optimism, Trade Realignment, and Market Volatility
Despite persistent macroeconomic headwinds, capital markets continue to derive substantial support from the advanced technology sphere. Heavy enterprise spending on computing facilities and software infrastructure has triggered a pronounced surge in electronics trade, lifting air cargo freight volumes internationally even as traditional maritime shipping routes experience contractions. Landmark capital-raising events, including high-profile public offerings within the artificial intelligence sector, have revitalized equity sentiment across major exchanges.
Nevertheless, analysts caution against growing concentration risk. The reliance of broader equity indices on a narrow cohort of technology leaders has left market valuations sensitive to shifts in corporate guidance and hardware delivery cycles. In parallel, traditional retailers are reporting mixed consumer patterns, noting that while higher-income households continue to drive discretionary spending, broader consumer baskets are feeling the cumulative drag of elevated fuel and utility costs.
Fiscal Tightening and the Path Forward
Looking toward the coming calendar year, sovereign balance sheets pose an increasingly visible structural risk. Public debt levels across major economies are projected to hover near or above full gross domestic output, leaving finance ministries with diminished scope to absorb further economic shocks. Escalating debt servicing costs increasingly threaten to divert resources away from productive public infrastructure, healthcare, and educational investments that underpin medium-term productivity growth.
To navigate these compounding pressures, economists emphasize the necessity of diversified trade partnerships, agile fiscal management, and coordinated international policy responses. While the ongoing technological buildout provides a foundational floor for global productivity, enduring stability will hinge on whether governments and central banks can tame underlying energy inflation without precipitating a broader liquidity squeeze.
Recommended for you
Similar to “Global Economy”
Fragile Resilience: Global Economy Navigates Energy Pressures, Rising Yields, and Tech Headwinds
While third-quarter output reflects ongoing momentum in key markets, rising sovereign bond yields, stubborn energy-driven inflation, and concentrated bets on artificial intelligence pose mounting risks to worldwide financial stability.
Uneven Resilience: Tech Investment and Mounting Debt Define a Shifting Global Economy
While robust capital spending on artificial intelligence and broad-based sectoral expansion continue to support global activity, policymakers warn that soaring sovereign debt, renewed energy shocks, and market volatility are straining the world economic outlook.
A Fragile Balancing Act: Soaring Energy Costs, Tech Whiplash, and Sovereign Debt Test the Global Economy
As persistent geopolitical strife and energy market shocks fuel stubborn inflationary pressures, central banks grapple with rising debt yields while the tech sector's heavy AI spending faces fresh scrutiny.